Quick Answer: Where Can I Finance A Lawn Mower?
You can usually finance a typical residential lawn mower through a store or dealer payment plan, manufacturer-backed promotional financing, a bank or credit union personal loan, another installment loan, or a credit card. Availability depends on the seller, new versus used, the amount, and your credit. Compare total cost, term, fees, and late-payment rules, not just the monthly amount. If dedicated…

Pros
- Powerful 80V brushless motor delivers 32HP gas-equivalent performance with quiet fume-free operation and no engine maintenance.
- Complete kit includes four 6.0Ah batteries and 600W charger for substantial runtime up to 1.5 acres.
- SmartCut technology and 42-inch heavy-duty steel deck ensure consistent cuts without bogging in tough conditions.
- Versatile towing up to 350 lbs and optional cargo hauling plus comfort features like high-back seat and LED lights.
- Strong 4-year limited warranty and full compatibility with the Greenworks 80V tool ecosystem.
Cons
- Rear utility cargo bed for 200 lb hauling is sold separately and not included in the kit.
- Runtime of up to 1.5 acres varies with conditions and may require recharging or battery swaps on larger properties.
- As a fully cordless model continuous operation depends on battery levels unlike gas engines with unlimited runtime.
The Greenworks 80V 42" CrossoverT Cordless Riding Lawn Tractor is a ready-to-mow zero-emission tractor designed for homeowners managing medium to large lawns. It features a reinforced 42-inch stamped steel deck of 12-gauge construction along with premium comfort elements such as a high-back padded seat with foldable armrests. The overall build emphasizes durability and user convenience right out of the box with the included battery and charger set.
Performance centers on the 80V TruBrushless motor that provides 32HP gas-equivalent power with instant torque and quiet fume-free operation. SmartCut technology senses grass conditions and automatically adjusts power to maintain a consistent cut even in tall thick or wet areas. The four 6.0Ah batteries support runtime for up to 1.5 acres depending on conditions while dual LED headlights and a 7-position deck height range from 1.5" to 4.5" add practicality. Front and rear attachments further allow towing up to 350 lbs for added yard utility.
Key considerations include that the rear utility storage bin capable of hauling 200 lbs is sold separately so full cargo functionality requires an extra purchase. Runtime remains condition-dependent and may fall short for properties significantly larger than 1.5 acres without using the 600W charger or swapping batteries. The cordless design prioritizes ease and low maintenance but trades off the continuous runtime of traditional gas models.
This tractor delivers strong value for eco-conscious owners of residential properties who want gas-like power without the emissions noise or upkeep. It suits those who already use or plan to expand into the Greenworks 80V family of tools and who appreciate the 4-year limited warranty. Users with exceptionally large or commercial-scale lawns should evaluate battery logistics carefully before purchase.

Pros
- Delivers strong 21 horsepower equivalent power comparable to gas riding mowers.
- Provides up to 1.5 acres of runtime on a full charge with the six included batteries.
- Features low-maintenance dual brushless motors without belts for greater durability.
- Offers versatile 12-position cutting height adjustment from 1.5 to 4.5 inches.
- Includes digital controls for blade settings, drive speeds, and cruise control.
Cons
- Limited to 1.5 acres of cutting per charge without purchasing additional batteries for bigger lawns.
- Requires recharging time for the six 56V batteries after each use session.
- Relies solely on battery power with no hybrid or gas backup option for extended operation.
The EGO Power+ TR4204 is a cordless electric riding lawn mower built as a modern tractor alternative for residential use. It features a robust 42-inch stamped steel deck and arrives ready to go with six 56V 6.0Ah batteries plus a charger, creating an immediate impression of convenience and solid construction free from gas engine complexity.
Performance shines through its equivalent 21 horsepower output and top speed of 6 MPH, allowing efficient coverage of up to 1.5 acres on a single charge. Dual brushless cutting motors operate without belts for added durability and less upkeep, while the digital display lets users select three blade settings, three drive speeds, and cruise control. The 12 adjustable heights ranging from 1.5 to 4.5 inches combined with anti-scalp wheels deliver precise results across varied terrain.
Drawbacks center on battery dependency, as larger properties beyond 1.5 acres require extra batteries and recharging intervals can interrupt workflow. The fully electric design eliminates fuel storage needs but demands access to power sources between sessions.
This mower suits homeowners with medium to large yards who value quiet, emission-free operation and reduced maintenance. Those seeking expandable battery capacity for bigger areas will find the EGO Power+ TR4204 a strong long-term investment in cordless lawn care.
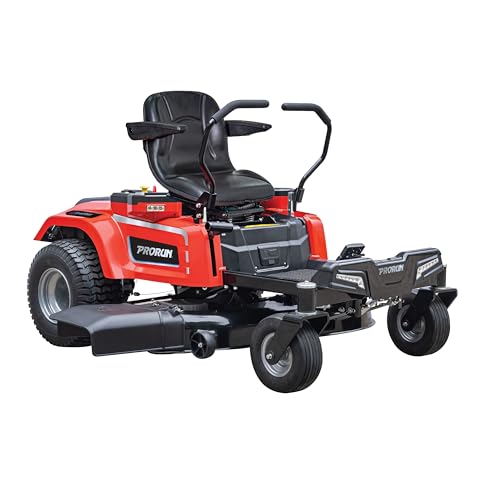
Pros
- High-efficiency brushless motors maximize power output and durability over traditional motors
- Up to 2 acres runtime with three included 10.0 Ah batteries supports substantial mowing sessions
- Zero-emission operation with gas-equivalent 20 HP power for quieter environmentally friendly use
- Six-port auto-switchover battery system provides flexible extended runtime options
- Durable 42-inch steel deck plus included mulch and towing kits add immediate functionality
Cons
- Runtime is limited to approximately 70 minutes or 2 acres which may require recharging for larger properties
- Fully battery-dependent design means performance relies on charge levels and spare battery availability
- 42-inch deck size may require more passes on expansive lawns compared to wider commercial models
The PRORUN PZT60V42 is a fully electric 60V zero-turn riding lawn mower built for residential and light commercial use. Its primary design centers on a robust 42-inch 14-gauge stamped steel twin blade deck powered by direct-drive brushless motors, giving an immediate impression of solid construction and modern battery-focused engineering. The mower arrives complete with three 10.0 Ah batteries, a charger, mulch kit, and towing kit for ready-to-work versatility.
In performance terms, four high-efficiency brushless motors deliver power equivalent to a 20 HP gas engine while producing zero emissions. The system supports up to 2.0 acres or 70 minutes of runtime, and six battery ports with auto switchover intelligently manage all PRORUN 60V battery sizes for continuous operation. A washout port on the steel deck further simplifies post-mow maintenance during real-world sessions.
Potential drawbacks include the finite 70-minute runtime window which can limit coverage on larger properties without spare batteries or recharge breaks. As a fully electric model, it also depends entirely on battery charge levels rather than continuous fuel refills, and the 42-inch deck width may demand extra passes compared with wider traditional options.
Overall the PRORUN PZT60V42 offers strong value for homeowners and small-property managers who want gas-like cutting power without emissions or noise. Those with medium-sized lawns seeking quiet efficient zero-turn performance and included accessories will benefit most from this electric mower.

Pros
- Strong 24HP FR730 engine power for demanding cutting conditions
- Wide 54-inch FAB deck reduces total mowing time
- Zero turn design delivers excellent maneuverability
- Fabricated deck supports durable everyday operation
Cons
- Sparse details beyond engine and deck leave other features unspecified
- Gas-powered FR730 engine needs regular fuel and maintenance
- Large 54-inch deck size may feel oversized on compact properties
The Husqvarna Z254F is a zero turn mower from the established Husqvarna brand in the riding lawn mowers category. It centers on a solid build that pairs a 24HP 726cc FR730 engine with a 54-inch FAB deck for straightforward residential grass care.
Performance stems directly from the listed specifications. The FR730 engine delivers the horsepower needed for steady operation across typical lawns while the wide FAB deck completes passes efficiently. Zero turn handling improves control in real yard layouts based on the model design.
Considerations arise from the limited data available. Secondary elements such as comfort features fuel capacity or extras receive no mention and the gas engine format involves routine upkeep. The large deck suits open areas better than confined spaces.
The Husqvarna Z254F provides the most value for owners of medium or large properties who want reliable engine power and a broad cutting width. Users with smaller lots or those seeking extensive accessory options should weigh the core specs carefully before purchase.
Where lawn mower financing usually comes from
Financing a lawn mower means spreading the purchase over time instead of paying the full cash price on the spot. For a home walk-behind or riding mower, that credit usually comes from a handful of categories, not from one universal program. The same categories can apply whether you shop a garden center, a farm-and-garden dealer, or a general retailer, but no seller is required to offer credit, and approval is never automatic.
Outdoor-power retailers and farm or garden dealers are often the first place people encounter an installment payment plan. Staff may offer to run an application at checkout so the mower, and sometimes delivery or attachments, can leave with you that day. Those plans are arranged to complete a specific sale. They may be limited to qualifying new equipment, a participating store, or a minimum purchase amount set by that seller’s finance partner.
Manufacturer promotional financing is a close cousin of in-store credit. A dealer or retailer presents an offer backed by the equipment maker’s finance partner. The paperwork still happens at the point of sale, and the credit is typically tied to that purchase rather than to cash you can spend anywhere. Promotional language may highlight deferred interest, an introductory period, or a low opening payment. Those features are marketing structures, not proof that the plan is cheaper than every other option.
Banks and credit unions sit in a different role. A personal loan from either institution is usually general-purpose money. You receive funds, then pay the seller yourself. That flexibility can matter if you are buying a used mower, shopping more than one store, or purchasing from a private party that will not run retail financing. Other installment lenders offer a similar product: a fixed-term loan that is not limited to one mower brand or aisle.
A credit card is revolving credit rather than a one-time installment plan. You can use an existing card, or a store may invite you to open a new one. Revolving accounts stay open after the mower is paid, and the cost depends on whether you carry a balance, what rate applies after any introductory period, and which fees the account charges. A card can be convenient for a smaller walk-behind mower or for a used machine sold without dealer financing. It is a poor default if you cannot pay the purchase down on a clear schedule.
Which path you meet first often depends on how you shop. People who walk into a dealer for a new riding mower are usually offered store or manufacturer financing before anything else. People who already have a bank or credit union relationship, who want to compare cash prices across sellers, or who are buying used equipment more often start with a personal loan or an existing card. Both a basic walk-behind mower and a larger riding mower can be financed through any of these categories if the seller participates and the amount is large enough for that lender’s process. A very inexpensive machine may be easier to put on a card or pay in cash than to run through a formal installment application.
How store, manufacturer, and personal-loan financing differ
The important difference is not the logo on the brochure. It is who is extending credit, what the credit is allowed to buy, and how flexible the arrangement is if your plans change.
Store or dealer financing at the point of sale
Store or dealer financing is designed to close a sale. The application, decision, and contract are usually handled while you are still at the counter. The credit is meant for that ticket: the mower and, if the seller allows it, related items on the same invoice. You typically cannot take the approval to a different shop or to a private seller. If the advertised cash price and the financed price are not the same, ask which price applies before anyone runs a credit check.
Manufacturer promotional financing through a dealer
Manufacturer promotional financing generally works the same way at the counter, with one extra layer: the offer is built to move qualifying new equipment from participating dealers. The plan may advertise a period that looks interest-free, a reduced introductory payment, or a special term on selected models. Those terms are not the same thing as a simple installment loan with a disclosed rate from day one. Deferred interest, in particular, can make the plan inexpensive only if every condition is met. If the balance is not paid as required, interest that was waiting in the background can be added. Read the contract for when interest starts, what “paid in full” means, and what a late or missed payment does to the promotion. To compare alternative configurations, check our hands-on review of marshall stanmore iii vs harman kardon onyx studio 8.
Personal loans from a bank or credit union
A personal loan is usually unsecured cash for a stated term, with a fixed payment if the loan is a standard installment product. Its purpose is broader than one mower. You can often use it at more sellers, including some private-party or used purchases that retail finance partners will not touch. Because the loan is not tied to a single store’s checkout, you can get the out-the-door cash price first and decide whether borrowing is still worth it. Flexibility has a tradeoff: you are responsible for paying the seller and for making the loan payments even if the mower later needs repair or you decide you bought the wrong size.
Installment plans versus revolving credit
An installment plan for one mower has a payoff date if you make every required payment. Revolving credit, such as a credit card, has a credit limit and a minimum payment that can leave a balance open for a long time. Installment credit makes the end date easier to see. Revolving credit can hide the true timeline if you only watch the minimum due. Neither structure is automatically cheaper. The comparison depends on APR, fees, term length, and how you actually repay. Users looking for related component recommendations can explore our dyson v8 cyclone vs bissell featherweight stick breakdown.
Security interest, in general terms
Some retail installment contracts and some other loans can give the creditor a security interest in the goods being financed. In plain language, the mower may stand behind the debt as collateral. That is a general credit concept, not a prediction of what any particular lender will do in your area. It matters at a high level because missing payments can put more than your credit file at risk, and because selling or trading the machine before the balance is cleared may require the creditor’s cooperation. Do not treat a salesperson’s summary as a legal opinion. The contract language controls.
What you usually need to apply
Most lenders and retail finance partners ask for the same core information: legal name, date of birth, government identification, current address, housing situation, income, and a way to contact you. They also ask for permission to run a credit check. Some in-store programs return a decision quickly. A denial at one seller does not mean every category of credit is closed. It only means that offer, on that day, with that application, was not approved. Before finalizing equipment decisions, refer to our comprehensive bissell crosswave hydrosteam vs shark stainforce comparison.
A credit check is common because the creditor is deciding whether to extend you money and on what terms. The inquiry can appear on a credit report. Comparing offers carefully before you submit several applications is wiser than letting every store run credit in the same afternoon. Consumer-credit practice sometimes treats a cluster of similar inquiries as rate shopping, but that treatment is not something to assume or try to game. The practical rule is simpler: gather prices and written terms first, then apply only where you are willing to accept the contract.
A down payment, proof of income, or a co-applicant can come up when the purchase is large, when the application is thin, or when the seller’s finance partner requires extra support. None of those items has a universal percentage or income multiple you should expect. If a store asks for a down payment, confirm whether it reduces the amount financed, whether it is refundable if the deal falls through, and whether optional products were added after you agreed on a machine price.
Before you allow a store to run credit, confirm a short list of facts in writing or on a worksheet you keep:
- The out-the-door cash price of the mower, including tax, assembly, and delivery if those apply.
- Exactly what would be financed: machine only, or also a trailer, bagger, blades, fuel, or an extended service plan.
- Whether the advertised price requires using that store’s financing.
- Whether the check will be a hard inquiry and whether you can see the full term sheet first.
- What happens if you are approved for a smaller amount than the ticket.
Do not omit or shade income, housing, or identity details to improve the odds. Underwriting is not a puzzle to beat, and a contract based on inaccurate information can create larger problems than a declined application.
What to compare before you sign
The advertised monthly payment is a scheduling number, not a measure of value. Two plans with the same payment can repay very different totals if the term, interest, fees, or add-ons differ. Judge an offer by the total cost of credit and by the rules that apply when life does not go as planned.
APR is the annualized cost of borrowing, including certain finance charges, expressed as a rate. It is the cleanest single figure for comparing a straightforward installment loan with another installment loan. It is less helpful if you are looking at a promotional plan with deferred interest, because the cost can jump if you miss the promotion’s conditions. The finance charge is the dollar cost of credit over the life of the plan if you follow the contract. Term length is how long you will be paying. A longer term can lower the monthly amount while increasing total interest whenever interest is charged.
A down payment reduces the amount financed if it is applied to the cash price. It does not make a high-cost contract cheap. Deferred interest is not the same as true interest-free billing. With deferred interest, finance charges may be calculated in the background and then added if you fail to pay the required balance by the deadline or if you miss a payment. True interest-free billing, when it actually exists in a contract, does not add that backlog. Do not rely on a banner or a verbal “same as cash” phrase. Ask which structure the contract uses and what event ends the promotion.
Fees, taxes, and extras change the amount you borrow. Sales tax, destination or setup charges, a trailer, attachments, and optional extended service plans can all be rolled into the financed total. Each extra earns interest if the plan charges interest. Delivery and assembly are easy to accept in the moment and easy to forget when you later compare the payment with the sticker you first noticed. Prepayment rules matter if you expect a bonus, a tax refund, or a seasonal cash influx. Some contracts allow early payoff without penalty; others are less flexible. Late fees, returned-payment fees, and default language matter more than people expect on a seasonal tool, because a mower payment can still be due in months when you are not cutting grass.
When you compare a promotional dealer plan with a bank or credit union personal loan, line up the same facts:
- Cash price versus amount financed after taxes and add-ons.
- When interest begins, and whether any interest is deferred.
- APR or finance charge if the plan is a conventional installment loan.
- Number of payments and whether the last payment is larger than the rest.
- Whether the credit can be used only at that store.
- What a late payment does to the rate, the promotion, and any security interest.
- Whether you can pay extra or pay off early without a fee.
No category is universally cheaper. A promotional plan can be inexpensive if you meet every condition and the add-ons stay off the ticket. A personal loan can be clearer if you want one rate, one payoff date, and the freedom to buy used or shop around. A credit card can be reasonable for a smaller balance you already know you will clear. None of these structures is free money, and none is no-risk.
New, used, and different mower types
Dedicated mower financing is more often offered on a new machine sold by a participating retailer or dealer than on a used private-party machine. Promotional and dealer plans are built around new inventory, warranty paperwork, and a seller who already has a finance partner. A private seller usually wants cash, a confirmed payment, or another method they can verify. A used mower from a dealer may still qualify for some in-house plans, but that is a store-by-store question, not a rule you can count on.
Mower type changes the mix of practical options mainly through price and complexity, not through a special legal category for homeowners. A basic walk-behind mower is often small enough that people pay cash, use a card, or skip credit entirely. A higher-priced riding mower or zero-turn machine creates a larger cash outlay, so installment credit becomes a more common conversation. That does not mean financing is required, and it does not mean a larger machine is a better candidate for debt. It only means sellers are more likely to mention payment plans when the ticket is bigger.
Commercial-grade equipment, or a mower bought for a business rather than a household lawn, is a different underwriting and tax situation. Applications may ask about the business, and the right way to treat interest or depreciation is not something a general consumer article can specify. If the machine is for paid work, pause and get advice from a qualified tax or business professional before you mix household credit with business use.
Trailers, baggers, extra blades, and extended warranties are sometimes offered as one bundled financed amount. Rolling them in can be convenient and can also hide how much machine you are actually buying. An extended service plan is optional in most consumer sales. Scrutinize whether you want that product at that price, whether it duplicates coverage you already have, and whether financing it for years makes sense on a tool that lives outside and loses value. If you would not buy the add-on with cash, be cautious about buying it with interest.
Alternatives if dedicated mower financing is not available or not a good fit
Dedicated financing is a tool, not a requirement. If a store does not offer it, if an application is denied, or if the total cost is hard to justify, several other paths still complete the job of keeping a lawn cut.
Paying cash or waiting and saving is the simplest option when the purchase is not urgent. Grass grows on a schedule, but a new machine does not have to. A few more weeks of a neighbor’s mower, a rental, or a one-time lawn service can bridge a season while you avoid a high-cost contract. Buying a less expensive walk-behind instead of a riding mower, or choosing a used or dealer-reconditioned unit, can shrink the cash gap without a loan. Used equipment is not guaranteed to be reliable, and a reconditioned unit is only as good as the inspection and any warranty the seller actually puts in writing. Still, a smaller cash purchase can be a better match than a long installment plan on a machine that is larger than the yard needs.
Borrowing or sharing equipment is another way to reduce the need for credit. Households that split a mower, a neighborhood tool library, or a short rental for the first heavy growth of spring can test how much machine you truly need. Renting is not always cheaper than owning, especially if you would use a mower every week for years. It can be cheaper than owning if your lot is small, your season is short, or you are not sure you want the maintenance.
A credit card or a general personal loan can still be reasonable when you have a written payoff plan, you understand the APR, and the payment fits after rent or mortgage, food, utilities, and other essentials. A short-term arrangement with a seller, such as a limited in-house hold or a deposit while you gather the balance, only makes sense if the terms are clear and you will not lose money if you walk away. Hiring a lawn service is sometimes the better comparison, particularly if you would finance a large riding mower for a yard that a crew can handle for a season while you decide.
Treat high-cost paths with extra caution. Rent-to-own, title-style credit, and payday-like products can be much more expensive than a conventional installment loan or a credit card paid on schedule. They are often a poor match for a depreciating outdoor tool. If the pitch emphasizes how easy approval is and stays vague about the total you will repay, walk through the numbers on paper before you sign, or walk away.
Risks that matter more than the monthly payment
Interest, fees, and add-ons can make a financed mower cost more than the ticket price you first compared across stores. That gap is the total cost of credit, and it is the figure that should sit next to the cash price. A longer term that “keeps the payment low” can quietly add months of finance charges. Optional products financed at the register do the same. If you cannot explain the difference between the cash price and the amount you will repay, you do not have enough information to sign.
Applying for credit can affect a credit file through inquiries and through the new account that appears if you are approved. Missing payments can trigger late fees, collection activity, and lasting damage on a credit report. Some retail plans can also place a security interest in the goods, which raises the stakes if the account goes unpaid. None of that is a reason to avoid every form of credit. It is a reason to treat a lawn mower loan with the same seriousness you would give any other multi-month obligation.
Promotional financing is easy to misunderstand. “Same as cash,” “no interest if paid in full,” and a low introductory payment can hide deferred interest, a balloon-style last payment, or a requirement that every payment arrive on time. The contract, not the hanging tag, decides when interest starts and whether missed payments make back interest due. If you cannot restate those rules in your own words, ask for a written explanation or choose a simpler installment loan.
Financing a rapidly depreciating outdoor machine is different from financing a home. A house may hold value and is a long-lived asset. A mower loses value as soon as it is used, sits in weather, and is replaced by newer models. If you need to get out of the deal early, you can owe more than the machine is easy to resell for. That is a cash-flow and resale problem, not a reason to panic, but it is a reason not to stretch the term just to make the monthly number look small.
Pause and get independent advice if you cannot afford the payment after essential expenses, if you do not understand when interest starts, or if you feel pressured to add insurance or warranties you do not want. A trusted nonprofit credit counselor, a bank or credit union officer who is not selling that mower, or another adviser who does not earn a commission on the contract can help you read the numbers. This article cannot tell you your rights in a specific country or what a court would do with a default. Local consumer-credit rules differ, and a qualified professional in your area is the right source for that kind of question.
A simple way to choose a path
Start with the job, not the payment. Decide what the yard actually needs: a walk-behind mower, a riding mower, or no purchase at all this season. Decide whether new or used is acceptable, and decide whether you need the machine immediately or can wait. Those choices set the cash budget. Include fuel, maintenance, storage, any trailer or extra blades, and the possibility of repairs. A payment that only covers the machine and ignores upkeep is not a complete budget.
Next, get the out-the-door cash price from the seller. Ask whether financing is optional or whether an advertised price requires using the store’s plan. If you will use credit, compare at least one non-store option, such as a bank or credit union personal loan or an existing credit card you can pay down on a known schedule. Read the full term sheet. Apply only when the total amount repaid, the term, and the late-payment rules are acceptable.
Questions worth asking a dealer or lender before an application is submitted include:
- What is the cash price if I do not finance?
- What exactly would be included in the amount financed?
- Is this a conventional installment loan, revolving credit, or a promotional plan with deferred interest?
- When does interest begin, and what ends any promotional period?
- What are the late fees, and what happens after one missed payment?
- Can I pay extra or pay the balance early, and is there a fee?
- Will this application create a hard credit check, and may I take the disclosures home first?
You have enough information to apply when you can state the cash price, the amount financed, the payment, the number of payments, the total you will repay if you follow the contract, and the consequence of a late payment. You have enough information to walk away if any of those items is missing, if the payment crowds out essentials, or if the only way the deal “works” is a term so long that the mower may be worn out before the balance is gone. Following these steps does not guarantee approval. It does keep the decision on the total cost of credit instead of on a monthly number that was designed to feel small.
Technical Standards and Compliance
Mechanical safety standards, operational tolerances, and protective gear guidelines align with benchmark specifications established by the American National Standards Institute (ANSI).