Direct Answer: Do You Need Insurance to Mow Lawns?
No, insurance is not legally required to mow your own lawn or for residential personal purposes. No federal or state law mandates coverage for private lawn mowing. However, if you mow lawns as a business, whether full-time or as a side gig, general liability insurance is a practical necessity. It protects you against property damage and injury claims, and many clients, HOAs, property managers, and municipalities require proof of coverage before you can work.

Pros
- Powerful 80V brushless motor delivers 32HP gas-equivalent performance with quiet fume-free operation and no engine maintenance.
- Complete kit includes four 6.0Ah batteries and 600W charger for substantial runtime up to 1.5 acres.
- SmartCut technology and 42-inch heavy-duty steel deck ensure consistent cuts without bogging in tough conditions.
- Versatile towing up to 350 lbs and optional cargo hauling plus comfort features like high-back seat and LED lights.
- Strong 4-year limited warranty and full compatibility with the Greenworks 80V tool ecosystem.
Cons
- Rear utility cargo bed for 200 lb hauling is sold separately and not included in the kit.
- Runtime of up to 1.5 acres varies with conditions and may require recharging or battery swaps on larger properties.
- As a fully cordless model continuous operation depends on battery levels unlike gas engines with unlimited runtime.
The Greenworks 80V 42" CrossoverT Cordless Riding Lawn Tractor is a ready-to-mow zero-emission tractor designed for homeowners managing medium to large lawns. It features a reinforced 42-inch stamped steel deck of 12-gauge construction along with premium comfort elements such as a high-back padded seat with foldable armrests. The overall build emphasizes durability and user convenience right out of the box with the included battery and charger set.
Performance centers on the 80V TruBrushless motor that provides 32HP gas-equivalent power with instant torque and quiet fume-free operation. SmartCut technology senses grass conditions and automatically adjusts power to maintain a consistent cut even in tall thick or wet areas. The four 6.0Ah batteries support runtime for up to 1.5 acres depending on conditions while dual LED headlights and a 7-position deck height range from 1.5" to 4.5" add practicality. Front and rear attachments further allow towing up to 350 lbs for added yard utility.
Key considerations include that the rear utility storage bin capable of hauling 200 lbs is sold separately so full cargo functionality requires an extra purchase. Runtime remains condition-dependent and may fall short for properties significantly larger than 1.5 acres without using the 600W charger or swapping batteries. The cordless design prioritizes ease and low maintenance but trades off the continuous runtime of traditional gas models.
This tractor delivers strong value for eco-conscious owners of residential properties who want gas-like power without the emissions noise or upkeep. It suits those who already use or plan to expand into the Greenworks 80V family of tools and who appreciate the 4-year limited warranty. Users with exceptionally large or commercial-scale lawns should evaluate battery logistics carefully before purchase.

Pros
- Delivers strong 21 horsepower equivalent power comparable to gas riding mowers.
- Provides up to 1.5 acres of runtime on a full charge with the six included batteries.
- Features low-maintenance dual brushless motors without belts for greater durability.
- Offers versatile 12-position cutting height adjustment from 1.5 to 4.5 inches.
- Includes digital controls for blade settings, drive speeds, and cruise control.
Cons
- Limited to 1.5 acres of cutting per charge without purchasing additional batteries for bigger lawns.
- Requires recharging time for the six 56V batteries after each use session.
- Relies solely on battery power with no hybrid or gas backup option for extended operation.
The EGO Power+ TR4204 is a cordless electric riding lawn mower built as a modern tractor alternative for residential use. It features a robust 42-inch stamped steel deck and arrives ready to go with six 56V 6.0Ah batteries plus a charger, creating an immediate impression of convenience and solid construction free from gas engine complexity.
Performance shines through its equivalent 21 horsepower output and top speed of 6 MPH, allowing efficient coverage of up to 1.5 acres on a single charge. Dual brushless cutting motors operate without belts for added durability and less upkeep, while the digital display lets users select three blade settings, three drive speeds, and cruise control. The 12 adjustable heights ranging from 1.5 to 4.5 inches combined with anti-scalp wheels deliver precise results across varied terrain.
Drawbacks center on battery dependency, as larger properties beyond 1.5 acres require extra batteries and recharging intervals can interrupt workflow. The fully electric design eliminates fuel storage needs but demands access to power sources between sessions.
This mower suits homeowners with medium to large yards who value quiet, emission-free operation and reduced maintenance. Those seeking expandable battery capacity for bigger areas will find the EGO Power+ TR4204 a strong long-term investment in cordless lawn care.
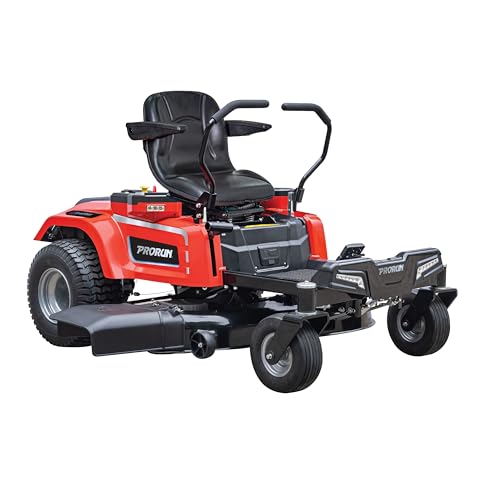
Pros
- High-efficiency brushless motors maximize power output and durability over traditional motors
- Up to 2 acres runtime with three included 10.0 Ah batteries supports substantial mowing sessions
- Zero-emission operation with gas-equivalent 20 HP power for quieter environmentally friendly use
- Six-port auto-switchover battery system provides flexible extended runtime options
- Durable 42-inch steel deck plus included mulch and towing kits add immediate functionality
Cons
- Runtime is limited to approximately 70 minutes or 2 acres which may require recharging for larger properties
- Fully battery-dependent design means performance relies on charge levels and spare battery availability
- 42-inch deck size may require more passes on expansive lawns compared to wider commercial models
The PRORUN PZT60V42 is a fully electric 60V zero-turn riding lawn mower built for residential and light commercial use. Its primary design centers on a robust 42-inch 14-gauge stamped steel twin blade deck powered by direct-drive brushless motors, giving an immediate impression of solid construction and modern battery-focused engineering. The mower arrives complete with three 10.0 Ah batteries, a charger, mulch kit, and towing kit for ready-to-work versatility.
In performance terms, four high-efficiency brushless motors deliver power equivalent to a 20 HP gas engine while producing zero emissions. The system supports up to 2.0 acres or 70 minutes of runtime, and six battery ports with auto switchover intelligently manage all PRORUN 60V battery sizes for continuous operation. A washout port on the steel deck further simplifies post-mow maintenance during real-world sessions.
Potential drawbacks include the finite 70-minute runtime window which can limit coverage on larger properties without spare batteries or recharge breaks. As a fully electric model, it also depends entirely on battery charge levels rather than continuous fuel refills, and the 42-inch deck width may demand extra passes compared with wider traditional options.
Overall the PRORUN PZT60V42 offers strong value for homeowners and small-property managers who want gas-like cutting power without emissions or noise. Those with medium-sized lawns seeking quiet efficient zero-turn performance and included accessories will benefit most from this electric mower.

Pros
- Strong 24HP FR730 engine power for demanding cutting conditions
- Wide 54-inch FAB deck reduces total mowing time
- Zero turn design delivers excellent maneuverability
- Fabricated deck supports durable everyday operation
Cons
- Sparse details beyond engine and deck leave other features unspecified
- Gas-powered FR730 engine needs regular fuel and maintenance
- Large 54-inch deck size may feel oversized on compact properties
The Husqvarna Z254F is a zero turn mower from the established Husqvarna brand in the riding lawn mowers category. It centers on a solid build that pairs a 24HP 726cc FR730 engine with a 54-inch FAB deck for straightforward residential grass care.
Performance stems directly from the listed specifications. The FR730 engine delivers the horsepower needed for steady operation across typical lawns while the wide FAB deck completes passes efficiently. Zero turn handling improves control in real yard layouts based on the model design.
Considerations arise from the limited data available. Secondary elements such as comfort features fuel capacity or extras receive no mention and the gas engine format involves routine upkeep. The large deck suits open areas better than confined spaces.
The Husqvarna Z254F provides the most value for owners of medium or large properties who want reliable engine power and a broad cutting width. Users with smaller lots or those seeking extensive accessory options should weigh the core specs carefully before purchase.
Understanding the Question: Legal Requirement vs. Practical Need
The answer to “Do I need insurance to mow lawns?” depends entirely on how you interpret “need.” There are two very different meanings:
- Legal requirement: Is there a law that forces you to buy insurance? For personal lawn mowing, the answer is no.
- Practical necessity: Is insurance required in practice to operate safely, satisfy clients, and protect your finances? For commercial lawn mowing, the answer is yes.
Understanding this distinction is critical because many readers ask the question while operating in one of these scenarios:
- Mowing your own residential lawn (no insurance needed, legally)
- Mowing a few neighbors’ lawns for cash as a side gig (no legal requirement, but clients may require it)
- Operating a registered lawn care business (no universal legal mandate, but industry standard and often contractually required)
Key Factors That Determine Whether You Need Coverage
Before deciding whether to buy insurance, evaluate your specific circumstances:
1. Are You Mowing Your Own Lawn or Offering Services to Customers?
This is the primary dividing line. If you are mowing only your own property, you do not need a separate business insurance policy. Your homeowner’s or renter’s insurance typically covers accidents on your property (though exclusions may apply if you operate a business from home).
If you are mowing for customers, even one neighbor for $50, you are operating a business, and the risk profile changes dramatically. You are liable for injuries to third parties and damage to their property. For additional operational safety benchmarks, see our published testing notes on z890 vs x870e motherboard.
2. Do Your Clients or Contracts Require Proof of Insurance?
Many residential and commercial clients require contractors to carry general liability insurance and provide a certificate of insurance before work begins. This is especially common for:
- Homeowners associations (HOAs)
- Property management companies
- Municipal or government contracts
- Commercial properties
- Larger residential estates
Even if the law does not require insurance, a client contract does. Without a certificate of insurance, you will not be hired. To compare alternative configurations, check our hands-on review of marshall stanmore iii vs harman kardon onyx studio 8.
3. What Are Your Financial Exposure and Assets?
If you cause property damage or someone is injured while you work, you could face a lawsuit. General liability insurance protects your personal assets (home, savings, vehicle) from being seized to pay a judgment. Without insurance, a single injury claim could financially devastate you.
4. Does Your State or Locality Require Special Licensing or Insurance?
While no federal law mandates insurance for lawn mowing, some states or municipalities may have specific licensing requirements or insurance clauses for commercial landscaping services. Check your local business licensing office or chamber of commerce. Users looking for related component recommendations can explore our dyson v8 cyclone vs bissell featherweight stick breakdown.
Step-by-Step Guide: Deciding What Coverage Fits Your Situation
Step 1: Identify Your Operating Model
Are you:
- A homeowner mowing your own lawn? No business insurance needed.
- Mowing lawns as a hobby or occasional side gig? Check client contracts; you may need coverage even for informal work.
- Operating a registered lawn care business? General liability insurance is standard practice.
Step 2: Review Client Agreements and Local Requirements
Before accepting any paid lawn mowing work, ask: Before finalizing equipment decisions, refer to our comprehensive bissell crosswave hydrosteam vs shark stainforce comparison.
- Does the client require proof of insurance?
- Do they require me to name them as “additionally insured” on my policy?
- Does my local jurisdiction require a business license or specific insurance for lawn care services?
Step 3: Compare Policy Types
The main insurance options for lawn mowing businesses are:
- General Liability Insurance: Covers bodily injury and property damage claims from third parties. This is the baseline policy for lawn care.
- Business Owner’s Policy (BOP): Bundles general liability, property coverage (for your equipment), and business interruption. Often more affordable than buying policies separately.
- Workers’ Compensation: Required in most states if you hire employees. Covers medical expenses and lost wages for injured workers.
- Personal Umbrella Policy: Provides additional liability coverage above your general liability limits. Useful if you want extra protection.
Step 4: Get Quotes and Confirm Coverage
Contact insurance brokers or agents and ask specifically about:
- Coverage limits (typically $1 million general liability is standard for small lawn care)
- What events are covered (property damage, bodily injury, equipment damage)
- What events are excluded (intentional damage, employee injuries without workers’ comp)
- Cost per year for your expected revenue and service area
Step 5: Obtain a Certificate of Insurance
Once you have a policy, your insurer will issue a certificate of insurance. This document proves you have coverage and can be provided to clients before work begins. Many clients require you to name them as “additionally insured,” which means they are also protected under your policy if an accident occurs.
Direct Answer: What Coverage Do Lawn Mowing Businesses Typically Need?
General Liability Insurance: The Baseline
General liability insurance is the foundational policy for lawn mowing businesses. It covers:
- Bodily injury: Medical expenses if someone is injured while you work (e.g., a bystander hit by flying debris from your mower)
- Property damage: Damage to the client’s property (e.g., you accidentally damage their fence, patio, or parked car)
- Legal defense: Lawyer fees and court costs if you are sued
For a small lawn mowing operation, general liability insurance typically costs $300-$800 per year, depending on your location, revenue, and claims history.
Do You Need Workers’ Compensation?
If you hire employees or contractors, you are required by law to carry workers’ compensation insurance in most states. This covers medical expenses and lost wages if an employee is injured on the job. If you operate as a solo contractor, you generally do not need workers’ compensation for yourself, though some states allow you to opt in for your own protection.
Is a Business Owner’s Policy (BOP) Worth It?
A BOP bundles general liability, property coverage (for your mower and equipment), and sometimes other protections. For a small lawn care operation, a BOP is often more economical than buying policies separately. It typically costs $500-$1,200 per year and provides broader protection.
Will My Homeowner’s Insurance Cover Lawn Mowing for Money?
No. Most homeowner’s insurance policies explicitly exclude business-related activities. If you mow lawns for payment and cause damage, your homeowner’s insurance will likely deny the claim. You need a separate business policy.
Common Scenarios and FAQs
Scenario 1: The Homeowner Mowing Their Own Lawn
You mow only your own residential property. You do not need business insurance. Your homeowner’s insurance covers accidents on your property. However, if you allow someone else (e.g., a friend or family member) to use your mower and they are injured, your homeowner’s policy may or may not cover it, check your policy language.
Scenario 2: The Weekend Side-Gigger
You mow lawns for a few neighbors on weekends for extra cash. Legally, no insurance is required. However, if any client asks for proof of insurance or requires it in a contract, you must obtain coverage or decline the job. Even informal, cash-based work can result in liability claims. A single injury or property damage incident could cost thousands. Many small operators in this position buy a general liability policy for $300-$500 per year to protect themselves and access more clients.
Scenario 3: The Full-Time Lawn Care Business
You operate a registered lawn care business with multiple clients, employees, or significant revenue. General liability insurance is industry standard and often contractually required. Most commercial clients, HOAs, and municipalities will not hire you without proof of coverage. If you have employees, workers’ compensation is legally required. A BOP or combination of general liability and property coverage is typical.
Everything You Need to Know: Do I Need Insurance To Mow Lawns FAQ
Q: I only mow a few neighbors’ lawns for pocket money. Do I really need insurance?
A: Legally, no. However, practically, yes, if a neighbor requires it in a contract or if you want to protect yourself financially. A single injury claim (e.g., someone hit by flying debris from your mower) or property damage claim (e.g., you damage their sprinkler system) could result in a lawsuit. Without insurance, you would pay out of pocket. General liability insurance for small operators costs $300-$500 per year and protects your personal assets. Many side-giggers buy a policy to access more clients and reduce financial risk.
Q: Can a client require me to carry insurance even if the law doesn’t?
A: Yes, absolutely. A client contract can require insurance as a condition of work. If you do not have coverage, you cannot accept the job. This is especially common for HOAs, property managers, and commercial clients. Even informal agreements (e.g., a handshake with a neighbor) may include an unspoken expectation of insurance. It is always wise to ask upfront: “Do you require proof of insurance before I start?”
Q: What should I do if I mow lawns but cannot afford a full policy yet?
A: Start by getting quotes from multiple insurers, costs vary significantly. Many small operators find that a basic general liability policy costs $300-$600 per year, which is manageable if you have even a few regular clients. If cost is still prohibitive, consider:
- Joining a trade association (e.g., National Association of Landscape Professionals) that may offer group insurance discounts
- Starting with only clients who do not require insurance, and upgrading to a policy as your business grows
- Buying a limited policy with lower coverage limits ($500K instead of $1M) to reduce cost
Q: Does insurance cover damage to my own mower or equipment?
A: General liability insurance does not cover damage to your own equipment. It only covers third-party bodily injury and property damage. If you want to insure your mower, equipment, and tools, you need property coverage, which is typically included in a Business Owner’s Policy (BOP) or purchased separately. This covers theft, damage, and loss of your equipment.
Key Takeaways
- No law requires insurance to mow your own lawn. Personal lawn mowing is not regulated.
- If you mow lawns for money, general liability insurance is a practical necessity, even if not legally mandated. It protects you against injury and property damage claims.
- Many clients require proof of insurance before hiring you. Without a certificate of insurance, you cannot access certain jobs.
- General liability insurance for lawn care typically costs $300-$800 per year and is one of the best investments for a small operator.
- If you hire employees, workers’ compensation insurance is legally required in most states.
- Your homeowner’s insurance does not cover business-related lawn mowing. You need a separate business policy.
- A Business Owner’s Policy (BOP) is often more economical than buying general liability and property coverage separately.
Liability Considerations for Mowing Work
Questions about coverage depend on local rules and the kind of work performed, so a licensed insurance professional is the right person to ask. For broad safety information aimed at people who mow lawns for others, American National Standards Institute (ANSI) is worth a look.