Quick Answer: Does Tractor Supply Finance Lawn Mowers?
Yes. Tractor Supply typically offers consumer financing that shoppers can use on eligible lawn mowers and similar outdoor power equipment. That path is usually a store credit account or another financing offer shown at checkout, not an automatic approval or a store-wide promise of zero interest. Whether a specific mower qualifies, and whether the offer appears in the store, online,…

Pros
- Powerful 80V brushless motor delivers 32HP gas-equivalent performance with quiet fume-free operation and no engine maintenance.
- Complete kit includes four 6.0Ah batteries and 600W charger for substantial runtime up to 1.5 acres.
- SmartCut technology and 42-inch heavy-duty steel deck ensure consistent cuts without bogging in tough conditions.
- Versatile towing up to 350 lbs and optional cargo hauling plus comfort features like high-back seat and LED lights.
- Strong 4-year limited warranty and full compatibility with the Greenworks 80V tool ecosystem.
Cons
- Rear utility cargo bed for 200 lb hauling is sold separately and not included in the kit.
- Runtime of up to 1.5 acres varies with conditions and may require recharging or battery swaps on larger properties.
- As a fully cordless model continuous operation depends on battery levels unlike gas engines with unlimited runtime.
The Greenworks 80V 42" CrossoverT Cordless Riding Lawn Tractor is a ready-to-mow zero-emission tractor designed for homeowners managing medium to large lawns. It features a reinforced 42-inch stamped steel deck of 12-gauge construction along with premium comfort elements such as a high-back padded seat with foldable armrests. The overall build emphasizes durability and user convenience right out of the box with the included battery and charger set.
Performance centers on the 80V TruBrushless motor that provides 32HP gas-equivalent power with instant torque and quiet fume-free operation. SmartCut technology senses grass conditions and automatically adjusts power to maintain a consistent cut even in tall thick or wet areas. The four 6.0Ah batteries support runtime for up to 1.5 acres depending on conditions while dual LED headlights and a 7-position deck height range from 1.5" to 4.5" add practicality. Front and rear attachments further allow towing up to 350 lbs for added yard utility.
Key considerations include that the rear utility storage bin capable of hauling 200 lbs is sold separately so full cargo functionality requires an extra purchase. Runtime remains condition-dependent and may fall short for properties significantly larger than 1.5 acres without using the 600W charger or swapping batteries. The cordless design prioritizes ease and low maintenance but trades off the continuous runtime of traditional gas models.
This tractor delivers strong value for eco-conscious owners of residential properties who want gas-like power without the emissions noise or upkeep. It suits those who already use or plan to expand into the Greenworks 80V family of tools and who appreciate the 4-year limited warranty. Users with exceptionally large or commercial-scale lawns should evaluate battery logistics carefully before purchase.

Pros
- Delivers strong 21 horsepower equivalent power comparable to gas riding mowers.
- Provides up to 1.5 acres of runtime on a full charge with the six included batteries.
- Features low-maintenance dual brushless motors without belts for greater durability.
- Offers versatile 12-position cutting height adjustment from 1.5 to 4.5 inches.
- Includes digital controls for blade settings, drive speeds, and cruise control.
Cons
- Limited to 1.5 acres of cutting per charge without purchasing additional batteries for bigger lawns.
- Requires recharging time for the six 56V batteries after each use session.
- Relies solely on battery power with no hybrid or gas backup option for extended operation.
The EGO Power+ TR4204 is a cordless electric riding lawn mower built as a modern tractor alternative for residential use. It features a robust 42-inch stamped steel deck and arrives ready to go with six 56V 6.0Ah batteries plus a charger, creating an immediate impression of convenience and solid construction free from gas engine complexity.
Performance shines through its equivalent 21 horsepower output and top speed of 6 MPH, allowing efficient coverage of up to 1.5 acres on a single charge. Dual brushless cutting motors operate without belts for added durability and less upkeep, while the digital display lets users select three blade settings, three drive speeds, and cruise control. The 12 adjustable heights ranging from 1.5 to 4.5 inches combined with anti-scalp wheels deliver precise results across varied terrain.
Drawbacks center on battery dependency, as larger properties beyond 1.5 acres require extra batteries and recharging intervals can interrupt workflow. The fully electric design eliminates fuel storage needs but demands access to power sources between sessions.
This mower suits homeowners with medium to large yards who value quiet, emission-free operation and reduced maintenance. Those seeking expandable battery capacity for bigger areas will find the EGO Power+ TR4204 a strong long-term investment in cordless lawn care.
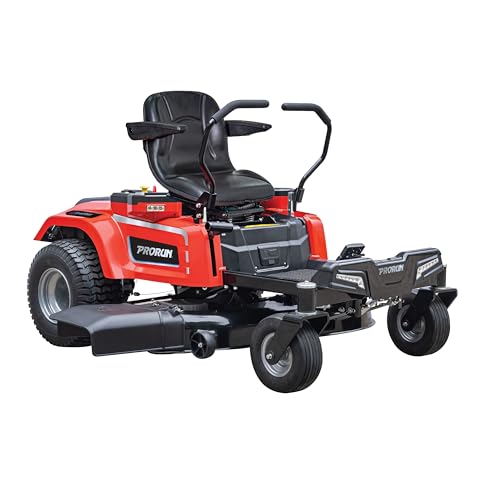
Pros
- High-efficiency brushless motors maximize power output and durability over traditional motors
- Up to 2 acres runtime with three included 10.0 Ah batteries supports substantial mowing sessions
- Zero-emission operation with gas-equivalent 20 HP power for quieter environmentally friendly use
- Six-port auto-switchover battery system provides flexible extended runtime options
- Durable 42-inch steel deck plus included mulch and towing kits add immediate functionality
Cons
- Runtime is limited to approximately 70 minutes or 2 acres which may require recharging for larger properties
- Fully battery-dependent design means performance relies on charge levels and spare battery availability
- 42-inch deck size may require more passes on expansive lawns compared to wider commercial models
The PRORUN PZT60V42 is a fully electric 60V zero-turn riding lawn mower built for residential and light commercial use. Its primary design centers on a robust 42-inch 14-gauge stamped steel twin blade deck powered by direct-drive brushless motors, giving an immediate impression of solid construction and modern battery-focused engineering. The mower arrives complete with three 10.0 Ah batteries, a charger, mulch kit, and towing kit for ready-to-work versatility.
In performance terms, four high-efficiency brushless motors deliver power equivalent to a 20 HP gas engine while producing zero emissions. The system supports up to 2.0 acres or 70 minutes of runtime, and six battery ports with auto switchover intelligently manage all PRORUN 60V battery sizes for continuous operation. A washout port on the steel deck further simplifies post-mow maintenance during real-world sessions.
Potential drawbacks include the finite 70-minute runtime window which can limit coverage on larger properties without spare batteries or recharge breaks. As a fully electric model, it also depends entirely on battery charge levels rather than continuous fuel refills, and the 42-inch deck width may demand extra passes compared with wider traditional options.
Overall the PRORUN PZT60V42 offers strong value for homeowners and small-property managers who want gas-like cutting power without emissions or noise. Those with medium-sized lawns seeking quiet efficient zero-turn performance and included accessories will benefit most from this electric mower.

Pros
- Strong 24HP FR730 engine power for demanding cutting conditions
- Wide 54-inch FAB deck reduces total mowing time
- Zero turn design delivers excellent maneuverability
- Fabricated deck supports durable everyday operation
Cons
- Sparse details beyond engine and deck leave other features unspecified
- Gas-powered FR730 engine needs regular fuel and maintenance
- Large 54-inch deck size may feel oversized on compact properties
The Husqvarna Z254F is a zero turn mower from the established Husqvarna brand in the riding lawn mowers category. It centers on a solid build that pairs a 24HP 726cc FR730 engine with a 54-inch FAB deck for straightforward residential grass care.
Performance stems directly from the listed specifications. The FR730 engine delivers the horsepower needed for steady operation across typical lawns while the wide FAB deck completes passes efficiently. Zero turn handling improves control in real yard layouts based on the model design.
Considerations arise from the limited data available. Secondary elements such as comfort features fuel capacity or extras receive no mention and the gas engine format involves routine upkeep. The large deck suits open areas better than confined spaces.
The Husqvarna Z254F provides the most value for owners of medium or large properties who want reliable engine power and a broad cutting width. Users with smaller lots or those seeking extensive accessory options should weigh the core specs carefully before purchase.
Does Tractor Supply Finance Lawn Mowers?
Tractor Supply is a farm-and-ranch retailer that sells walk-behind, riding, and zero-turn lawn mowers along with related outdoor power equipment. Like many large hard-goods retailers, it typically provides a consumer financing path so a customer can pay for eligible merchandise over time instead of paying the full ticket in cash or with an existing bank card.
That is the stable answer to the yes-or-no question. It is not the same as a guarantee that your particular mower, store, or shopping session will show financing, and it is not a promise that you will be approved. A financing program can exist while a given SKU is excluded, a promotional banner is expired, an online cart does not surface an application module, or an issuer declines the application. Availability of a program and approval of a person are two different things. For additional operational safety benchmarks, see our published testing notes on jbl partybox club 120 vs sony srs xv500.
Treat the following as reasonably stable: Tractor Supply sells lawn mowers; it typically offers store financing or a store credit account that can cover eligible purchases; customers can still pay with cash, debit, or a card they already have; and any advertised promotion is time-limited and offer-specific. Treat the following as something to verify at checkout or with a store associate that day: whether this exact mower is eligible, whether the offer appears in your channel, what the credit agreement actually says, and whether a new account’s available credit would cover the full amount after tax and add-ons. For additional operational safety benchmarks, see our published testing notes on jbl partybox club 120 vs sony srs xv500.
Nothing in a general article can substitute for the live offer. Older ads, social posts, and word of mouth go stale quickly. If someone told you the store “always” runs a long promotional period, or that every mower on the floor can be put on a new account, treat that as a rumor until the current checkout flow or printed terms say so. To compare alternative configurations, check our hands-on review of z890 vs x870e motherboard.
How Tractor Supply Purchase Financing Usually Works
When people ask whether Tractor Supply finances lawn mowers, they usually mean one of three paths, not a special tractor loan invented only for grass equipment.
Store credit versus money you already have
The most common in-store path is a Tractor Supply credit card or store credit account. In retail terms, that is a revolving account branded for the merchant. If you are approved, you receive a credit limit and can charge eligible store purchases up to that limit, then repay according to the account agreement. The account is a credit product. It is not a gift card, a manufacturer rebate, or an in-house layaway plan, even if the application happens at a register. To compare alternative configurations, check our hands-on review of z890 vs x870e motherboard.
That is different from paying with cash, a debit card, or a Visa, Mastercard, American Express, or other card you already carry. Those methods do not require a new Tractor Supply application. They also do not automatically inherit any store promotional language you may see on a sign. If you already have a personal loan, a home-equity product, or a credit union equipment loan, that financing lives outside the store. Tractor Supply would simply take payment the way it takes any other tender. The store’s job in that case is to complete the sale, not to underwrite your outside loan.
Some visits also surface a separate financing offer at checkout, sometimes aimed at a larger ticket. Those offers, when they exist, are still credit. They have an issuer or financing partner, written terms, and eligibility rules. This article cannot name a current partner, quote an annual percentage rate, or list a promotional length, because those details change and belong only in the live agreement. Users looking for related component recommendations can explore our marshall stanmore iii vs harman kardon onyx studio 8 breakdown.
Promotional language is not a blank check
Retail signs often talk about special financing, deferred interest, or a promotional annual percentage rate. Those phrases are not interchangeable, and none of them means “this mower is free until a date on the calendar.”
A true promotional APR, when one is offered, typically charges interest at a stated promotional rate for a defined period if you follow the rules in the agreement. Deferred-interest language, when that is the structure, often means interest can be charged retroactively if the promotional balance is not paid in full by the deadline or if other conditions are missed. Some offers mix a promotional period with a standard variable rate afterward. Fees, penalty pricing, and minimum-payment rules, if any, live in the same document. Before finalizing equipment decisions, refer to our comprehensive dyson v8 cyclone vs bissell featherweight stick comparison.
You cannot tell which structure you are looking at from a window decal. You tell by reading the current offer and the full credit agreement. If the associate summarizes the deal in a sentence, treat that as a pointer to the paperwork, not as the contract. Advertised promotions are also time-limited. A program that ran last spring may be gone, shortened, lengthened, or limited to selected merchandise this week.
What a financed ticket can include
Program rules decide whether financing covers only the mower or also attachments, blades, batteries, oil, delivery, assembly, extended protection, or other add-ons in the same cart. There is no universal rule that every line item rides along, and there is no universal rule that extras are excluded. Taxes and local fees can change the amount you need approved. If the associate is building a ticket that includes setup or a ship-to-store special order, ask whether those charges are eligible before you apply, and ask what happens if part of the order is delayed or cancelled after an account is opened. For broader ecosystem context, read through our operational guide on bissell crosswave hydrosteam vs shark stainforce.
A store credit account, once open, is typically meant for eligible Tractor Supply merchandise rather than for one isolated SKU forever. Future purchases, returns, and credit-limit changes follow the account agreement, not the original mower box.
In-Store Versus Online Lawn Mower Purchases
Channel is one of the main reasons two shoppers get two different answers. In-store and online checkout are related, but they are not guaranteed to show the same financing module on the same day for the same mower.
On the sales floor
If you are looking at a floor model or an in-stock unit, the practical first step is to ask an associate whether financing is being offered on that item right now and where you can read the terms. Associates can usually point you to eligible merchandise, the application device or paper process, and the current promotional poster or register prompt. They cannot promise approval, invent a rate, or override an issuer’s underwriting decision.
In-stock riding mowers and zero-turns are the purchases people most often try to finance in person, simply because the ticket is larger. Walk-behind units may still be eligible under the same merchandise rules. Special-order machines, assembled units, and delivered equipment can follow extra checkout steps. Confirm whether the financed amount is authorized before the order is placed, after it arrives, or in stages, and what you owe if the machine never comes in the configuration you expected.
On the website
The website does not have to display a financing button on every lawn-mower product page or in every cart. Online modules, when they appear, typically show only on eligible items and can differ from what a nearby store is offering. Some products that finance easily on the floor may check out online as a standard card or pay-in-full purchase. The reverse can also happen: a web page may surface an application that a particular store’s register is not highlighting that afternoon.
If financing appears in one channel and not the other, do not assume the missing channel is broken or that the visible channel is a loophole. Confirm eligibility in the channel you actually intend to use. If you need delivery, assembly, or a ship-to-store workflow, complete that conversation before you submit personal financial information. A financed online order can still be subject to inventory, shipping cutoffs, and return rules that have nothing to do with the credit decision.
There is no reliable hard rule that online orders can never be financed, and no reliable hard rule that every store always has an application ready for every guest. The current checkout flow is the authority.
Which Lawn Mowers and Related Purchases May Qualify
Eligibility is usually a merchandise-and-program question, not a mower-type question. The financing offer’s rules define which SKUs, categories, and purchase types qualify. This article cannot list today’s included and excluded items, and it cannot say that used, clearance, open-box, rental, commercial, or special-order equipment is or is not financeable at this moment.
It is fair to say that shoppers more often finance higher-ticket riding and zero-turn mowers than inexpensive walk-behind units. Price, not a secret exclusion of push mowers, is the usual reason. A smaller mower might still be eligible if it falls inside the program’s merchandise rules and the applicant is approved for enough credit. A large zero-turn might still be ineligible if it is the wrong condition, the wrong fulfillment method, or outside a promotional category.
Related outdoor power equipment sits in the same gray zone. Trimmers, blowers, generators, trailers, and attachments may or may not share the mower’s eligibility. Bundling them to “make a minimum” only works if a minimum exists in the current offer and those extras are allowed. Do not invent a dollar threshold from memory, and do not assume a kit price you saw last year still governs the account.
Personal use versus farm or business use can change the questions you should ask, even when the same machine is on the ticket. A store credit account is typically underwritten as consumer credit. If you intend to use the mower in a business, ask whether the offer in front of you is a consumer product, whether a commercial account exists, and how you should describe the purpose honestly on the application. Tax treatment of interest or equipment is not something a register prompt can settle. That belongs with your own tax advisor. Do not treat store lore as accounting advice, and do not misstate the purpose of the purchase to fit an offer.
Condition matters because program rules often do. A new crated mower, a display model, an open-box return, and a used trade-in are not automatically the same SKU for financing purposes. If the unit is discounted, ask whether the discount and the financing can be combined, and whether the serial-numbered machine in front of you is the one the system will ring as eligible.
How to Confirm an Offer Before You Apply
Confirming an offer is a short sequence. Applying is a credit decision. Keep those steps in that order.
Questions to ask in the store
Ask whether the specific mower, including its condition and fulfillment method, is eligible for the financing being advertised. Ask whether the advertised promotion applies to this ticket or only to selected categories. Ask where you can read the full terms, including what happens if a promotional balance is not paid as required. Ask whether delivery, assembly, attachments, and tax can be included. Ask how returns or cancelled special orders affect a new account. Write down or photograph the offer identifier if the store provides one, so you are not relying on a verbal summary later.
If two signs disagree, or if the register prompt does not match the poster, stop and reconcile that before you submit an application. Staff can explain the prompt they see. They cannot rewrite the issuer’s terms.
What to look for online
On a product page, cart, or checkout screen, look for language that the item is eligible and for a link or disclosure that opens the actual offer. Absence of a module is information: that session may not include store financing. Presence of a module is not approval. Read the disclosure in the same browser session you would use to apply, because offers can be targeted, geo-limited, or rotated.
If the site lets you estimate a payment, treat that figure as an illustration tied to assumptions you may not meet. This article will not invent sample monthly payments. Your real payment depends on the approved amount, the rate and fees in the agreement, promotional rules, and how you actually repay.
What an application commonly requests
Retail credit applications commonly ask for identifying information, contact details, and financial context such as income or housing information. The exact fields are set by the issuer and the current form, not by a lawn-mower aisle. Submitting the form can involve a credit check. That is a real inquiry on your credit file when the issuer pulls it, and it is a financial decision even if the tablet makes it feel like a loyalty signup.
This article cannot state Tractor Supply’s document list, credit-score cutoffs, approval odds, or decision speed, because those are underwriting details that are not for a general explainer to invent. If the form asks a question, answer it accurately. Do not inflate income, invent a job, or misstate whether the mower is for household or business use.
Pause before you apply if any of the following is unclear: the exact dollar amount that would be financed, whether tax and add-ons are included, whether your likely credit limit would cover the ticket, when the machine will be in your possession, and what you owe if the order changes. Opening an account to “hold” a mower you have not confirmed is how people end up with credit and no equipment, or equipment and a balance they did not plan to carry.
What to Weigh Before Financing a Mower
The useful comparison is not “finance versus be unable to cut grass.” It is the total cost and risk of store credit versus paying another way, buying a less expensive machine, waiting for a sale, or delaying the purchase until you can pay without new debt.
Total cost beats a low advertised payment
A low monthly payment can hide a long payoff, interest after a promotional window, or fees. The number that matters is what you will pay in total if you follow the plan you can actually keep, including what happens if you only make minimum payments. If the offer is deferred interest, missing the promotional payoff can make the product far more expensive than the aisle sign suggested. If the offer is a promotional APR that then moves to a standard rate, the second chapter of the loan is part of the price.
Identify the structure in the actual terms. Do not assume Tractor Supply is currently running one type of promotion or the other. Both structures exist in retail generally. Only the agreement in your hand tells you which one, if either, applies today.
Credit limit, ticket size, and add-ons
Approval can come back as a yes with a limit below the mower’s price after tax, delivery, and attachments. That is not a store trick; it is how revolving credit works. Before you count on financing the whole machine, confirm how a shortfall would be handled: a second tender, a smaller mower, fewer add-ons, or walking away. Do not assume a new account will be raised on the spot to match a zero-turn you have already loaded on a trailer.
If you are declined, that is an issuer decision. Reapplying immediately, shopping every register in the district, or asking staff to “try again” is not a strategy this article can endorse, and staff cannot override underwriting. Use the adverse-action information the issuer provides if you want to understand the decision. Credit-repair shortcuts and advice on beating a credit check do not belong in a mower-financing explainer.
When another tender is more predictable
Cash, debit, or an existing card can be the cleaner choice when you can pay without straining the rest of your budget, when the promotional conditions look easy to miss, when the credit limit is uncertain, or when you do not want a new tradeline. Waiting for a merchandise sale can also change the cash price; financing a full-price machine to chase a promotion is only a win if the credit terms beat the discount you would otherwise get, and that math depends on numbers this article does not have.
A less expensive walk-behind or a used machine paid in full can be more predictable than a financed premium rider, even if the rider is eligible. Predictability is a feature. So is the ability to return or exchange without also managing a new revolving balance.
If you already carry high-interest balances, adding a mower to a new store account does not automatically improve your situation. If the mower is essential for income-producing land, that still does not make an unaffordable payment a good tool. Affordability is your budget, not the store’s willingness to take an application.
Caveats, Changing Offers, and Where to Get Authoritative Details
Two customers, two stores, or two days can show different financing options because programs, partners, eligible products, and promotional language change. Geography, inventory, channel, and the applicant’s credit file all sit outside a general article. A display mower in one market is not a policy for the chain.
Store staff can explain what the register or poster shows, help you locate eligible items, and start or point to an application. They typically cannot change an APR, guarantee an approval, raise a limit on demand, or promise that a declined application will succeed after a small tweak. Underwriting belongs to the financing partner. Courtesy and product knowledge on the floor are not the same as credit authority.
The authoritative details live in three places: the live offer at checkout, the credit agreement and account opening disclosures, and customer service for Tractor Supply or the financing partner named on those documents. Those materials are where rates, fees, promotional conditions, and billing questions belong. This article is not a live rate sheet, not an approval guarantee, not legal advice, and not tax advice. It cannot promise a payment, a decision time, or that a particular mower in a particular store can be financed this afternoon.
If you need numbers, open the current offer. If you need to know whether a used, open-box, commercial, or special-order machine qualifies, ask on that ticket. If you need to know whether delivery or assembly can be included, ask before the application, not after the issuer replies. And if you decide store financing is not worth the complexity, paying another way is still a complete answer to the original question: Tractor Supply typically can finance eligible lawn mowers, but you are never required to use that path to buy one.
Buyer FAQs: Does Tractor Supply Finance Lawn Mowers Solved
Is Tractor Supply lawn mower financing the same as a guaranteed approval?
No. A program can be available while an individual application is declined or approved for less than the ticket. Creditworthiness, the current offer, and program rules all matter. Associates cannot guarantee the outcome.
Can I finance a walk-behind mower, or only riders and zero-turns?
Eligibility usually follows the financing program’s merchandise rules, not the cutting deck style. Riders and zero-turns are financed more often because they cost more, not because walk-behind mowers are automatically excluded. Confirm the specific SKU.
Does online checkout always offer the same financing as the store?
Not necessarily. Online modules, when shown, typically appear only on eligible items and can differ from in-store prompts. Use the channel you intend to buy in as the source of truth.
Will financing cover delivery, assembly, and attachments?
Only if the current program treats those line items as eligible and they are on the same qualifying ticket. Ask before you apply. Do not assume extras are included or excluded.
What should I read before I submit the application?
Read the full credit agreement and any promotional disclosure, including how interest works if you miss a promotional payoff, what fees may apply, and how returns affect the balance. If the financed amount, credit limit, or delivery timing is unclear, wait.
For more detailed testing breakdowns and top recommendations, check our in-depth guide to residential zero-turn lawn mower guide.
For more hands-on benchmarks and buying recommendations, consult our guides on heavy-duty chainsaw buyer guide, as well as high-CFM commercial leaf blower guide, as well as automated robotic lawn mower guide.
Mechanical safety standards, operational tolerances, and protective gear guidelines align with benchmark specifications established by the American National Standards Institute (ANSI).